We Negotiated $200,000 Off a Fort Worth House. Here's What That Says About the Market Right Now.
· 4 min read
Our team just negotiated $200,000 off the list price of a Fort Worth home — on top of a $100,000 price cut before we ever wrote the offer. That doesn't happen in a frenzy market. Here's what's happening right now with rates, price reductions, and ARMs, and why "marry the house, date the rate" is the play for buyers in 2026.
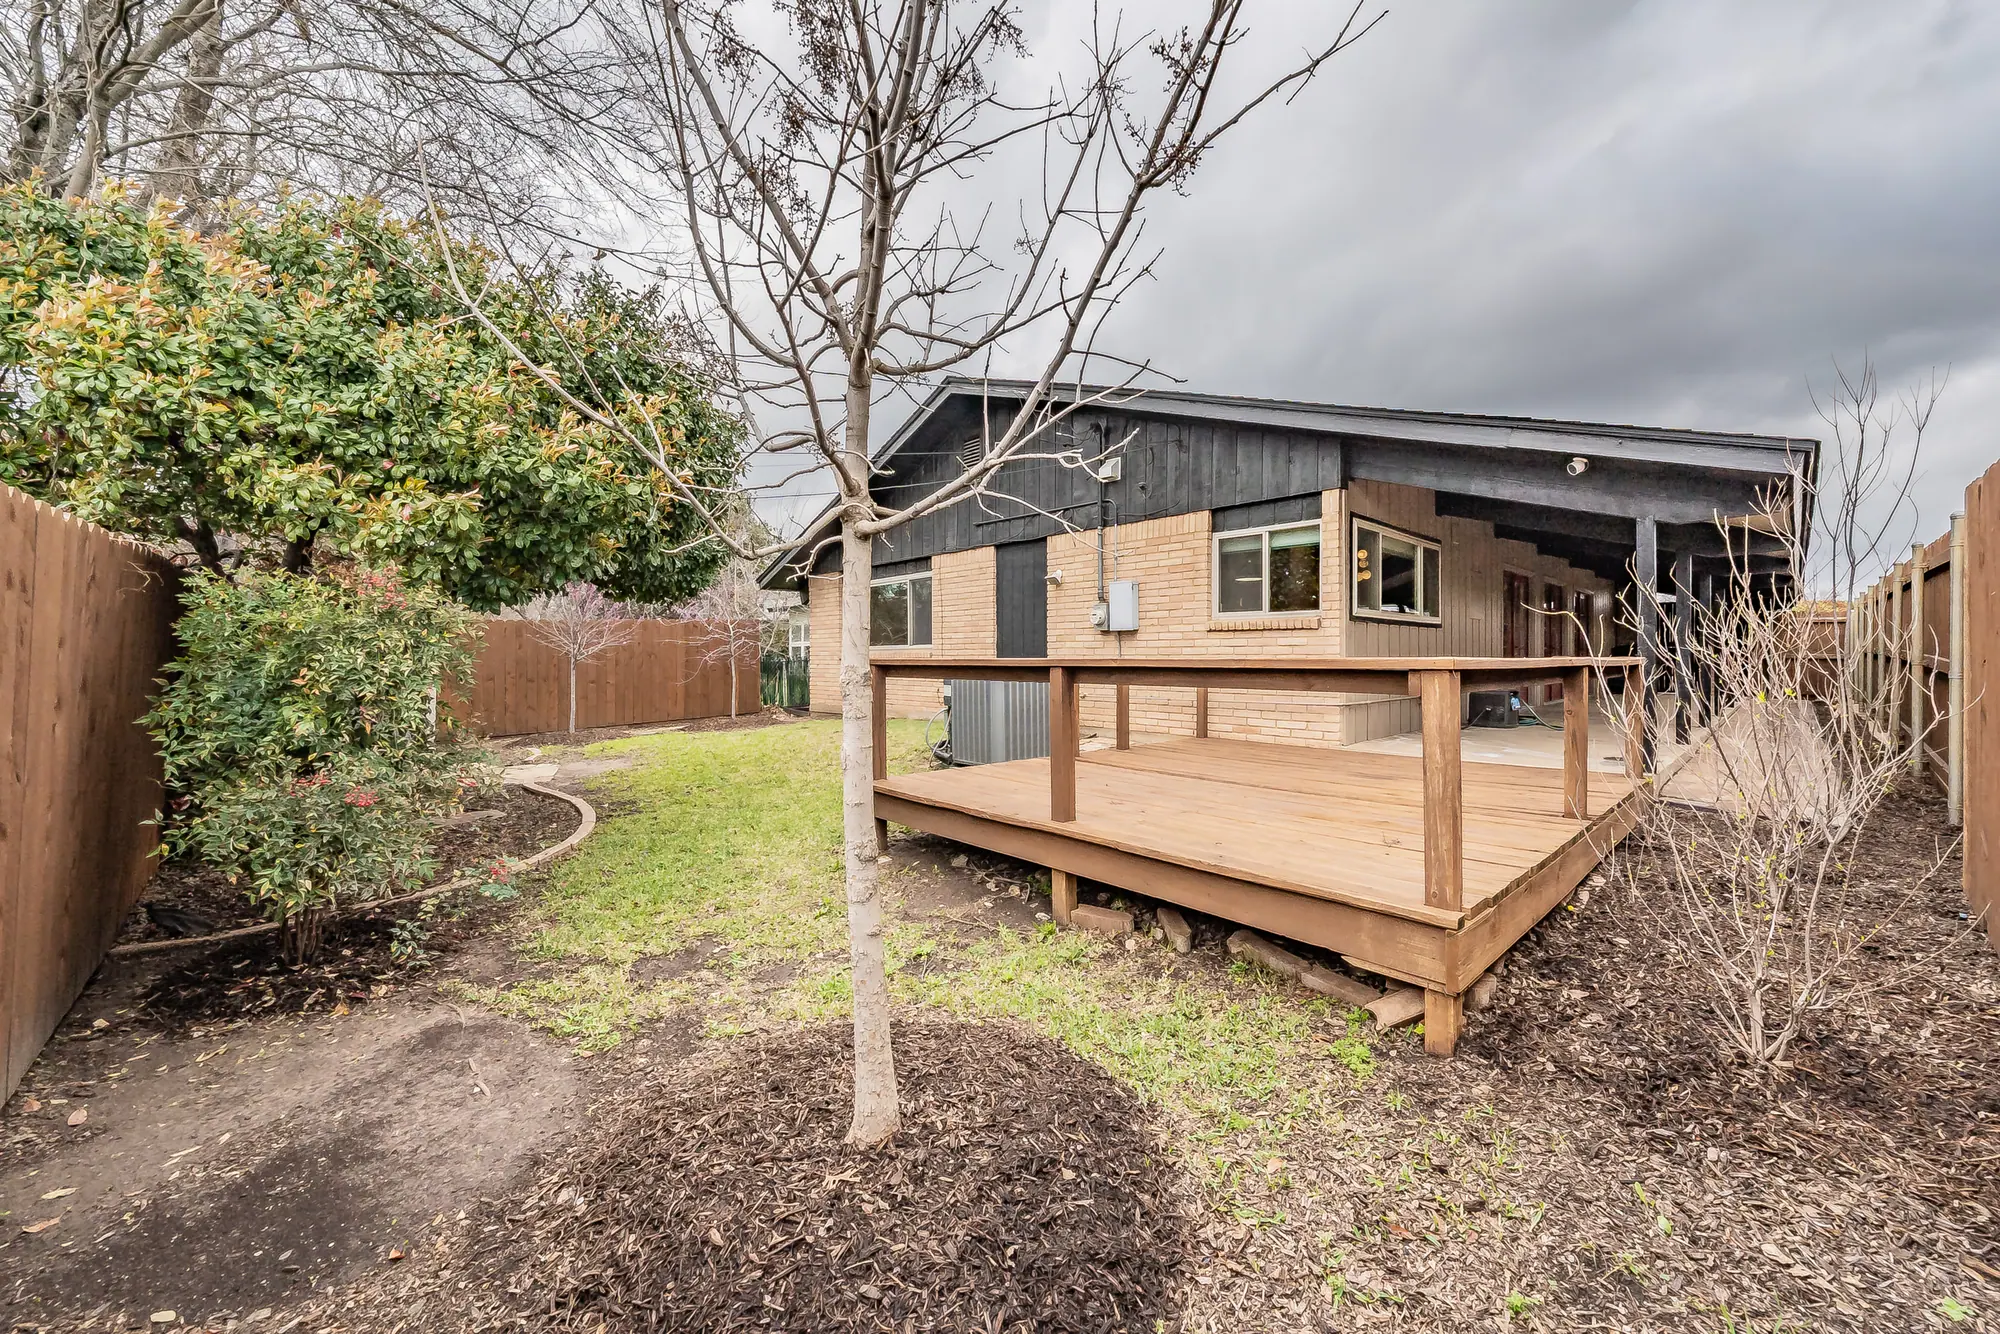
A few weeks ago, our team helped negotiate $200,000 off the list price of a house for our clients.
And that's not even the whole story. That house had already dropped $100,000 before we ever wrote an offer. So our buyers are closing on a home for $300,000 less than it was originally listed for.
That doesn't happen in a frenzy market. It happens in a market like this one.
What's Actually Happening Right Now
Interest rates just hit 6.9%, the highest they've been in over a year. That stings, and nobody's pretending it doesn't.
But the flip side is real. We're seeing more price reductions than we've seen in a long time. Homes are sitting longer. Sellers who priced for 2022 are finally coming down to 2026. And after a few years of pure chaos, things are balancing out.
Which means if you're a buyer, you've got something you haven't had in years: room to negotiate.
Room to ask for repairs.
Room to ask for closing costs, or a rate buydown.
Room to make an offer that would've gotten you laughed out of the room in 2021 — and actually have it land.
Marry the House. Date the Rate.
Here's the thing about high rates. You can't go back and buy at today's prices once the market heats up again. But you can refinance when rates come down. And they will come down at some point. They always do.
So the play right now isn't to wait. It's to buy the house you actually want, negotiate hard, and treat the rate like it's temporary. Because it is.
The Option Almost Nobody Is Talking About: ARMs
Adjustable-rate mortgages got a bad name in 2008, and most people wrote them off for good. But we've had a few clients go that route recently, and it's worth a look.
Right now a 5-year ARM is running about a full point under a 30-year fixed — 5.82% versus 6.85% in a recent week, according to the Mortgage Bankers Association. On a $500,000 loan, that's a little over $300 a month in principal and interest.
You can refinance a rate later; you can't go back and renegotiate the purchase price.
If you already plan to refinance when rates drop, or you don't see yourself in the house for 30 years, you might be paying for a fixed rate you'll never use. An ARM is the most literal version of dating the rate there is.
It's not for everyone. The rate does adjust after the initial fixed period, and you need to be comfortable with that risk. But it's worth a conversation — and our lenders will give it to you straight.
If You're Selling
Don't panic. Well-priced, well-presented Fort Worth homes are still moving. It just takes strategy now instead of luck. Pricing to today's comps (not 2022's), preparing the house properly, and knowing when a small pre-listing fix is worth it — that's what our Guides are for.
The House That "Needs a Little Work" Is Suddenly a Great Deal
One more angle worth thinking about. Because you can buy lower right now, the house that needs some work is suddenly one of the best opportunities in the market. Buy it right, then renovate it into exactly what you want — kitchen, bath, addition, pool, whatever it is.
That's the part most brokerages can't help you with. We can. Our agents, designers, construction team, and lenders all sit under one roof, so you can figure out the purchase price and the renovation budget in the same conversation — before you write the offer, not after you close.
The Bottom Line
If you've been sitting on the sidelines waiting for the market to make sense again, this is what that looks like. Not perfect. But workable. And full of opportunity for people who are paying attention.
Free consultation, like always. Tell us what you're looking for and we'll show you what negotiating room actually looks like in your price range and neighborhood right now.
And if you're curious what your current place is worth, we'll run a free CMA. No pressure. Just good info.
Frequently Asked Questions
Is now a good time to buy a house in Fort Worth? For buyers who are ready, yes. Rates are near 7%, but price reductions and seller concessions are more common than they've been in years. You can refinance a rate later; you can't go back and renegotiate the purchase price.
Can I negotiate the price on a Fort Worth home in 2026? Yes. Homes are sitting longer and price cuts are common. Buyers are successfully negotiating price reductions, repair credits, closing cost help, and rate buydowns.
What is a rate buydown? A buydown is when the seller (or buyer) pays upfront to lower the mortgage interest rate, either permanently or for the first few years of the loan. In a buyer-leaning market, asking the seller to fund a buydown is often more valuable than an equivalent price cut.
Is an adjustable-rate mortgage a good idea right now? It can be. A 5-year ARM has recently run about a full percentage point below a 30-year fixed. It makes the most sense if you plan to refinance or move within the fixed period, and you understand the rate can adjust afterward.